
By Julius Peter
Nigeria’s external reserves have risen to about $54 billion, their highest level in nearly 18 years, marking a significant improvement in the country’s foreign-exchange position and strengthening the Central Bank of Nigeria’s (CBN) capacity to support stability in the naira and the wider economy.
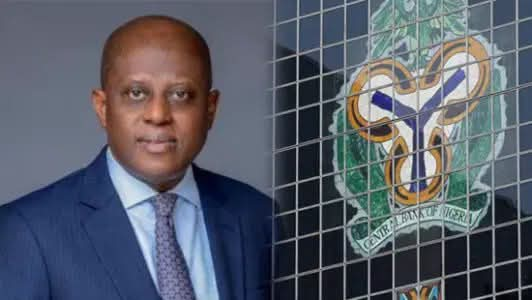
CBN Governor, Olayemi Cardoso, disclosed the development, describing the sustained accumulation of foreign reserves as an indication of improving foreign-exchange inflows and greater resilience in Nigeria’s external position.
The reserves, which stood at approximately $54.08 billion as of September 3, 2026, represent the highest level recorded since December 2008, when Nigeria’s reserves were around $54.21 billion.
The latest figure also represents a substantial increase from the approximately $45.56 billion recorded at the beginning of the year, translating into an increase of more than $8 billion.
The development comes at a critical period for Nigeria, as the government and monetary authorities continue efforts to stabilise the foreign-exchange market, strengthen investor confidence and rebuild the country’s external buffers.
Cardoso attributed the improvement in reserves to stronger foreign-exchange inflows into the country, including receipts associated with crude oil and other sources.
The increase suggests that Nigeria has been able to retain and accumulate more foreign currency at a time when authorities have been implementing measures aimed at improving transparency and liquidity in the foreign-exchange market.
The CBN has in recent months maintained its focus on strengthening the functioning of the FX market, reducing distortions and ensuring that genuine demand for foreign currency can be met more efficiently.
For an economy such as Nigeria’s, where crude oil remains a major source of foreign-exchange earnings, the level of external reserves is closely watched by investors, businesses and international institutions.
A stronger reserve position provides the country with a larger cushion against external shocks, including fluctuations in crude oil prices, disruptions in foreign-exchange inflows and periods of heightened demand for dollars.
The latest reserve figure is particularly significant because it takes Nigeria back to a level last seen during the commodity boom of the late 2000s.
Nigeria accumulated substantial reserves during the period of relatively high international crude oil prices. However, the country’s external buffers subsequently came under pressure as oil prices fell, production challenges intensified and foreign-exchange demand increased.
The recovery to above $54 billion therefore represents a major turnaround in Nigeria’s external position.
It also comes after several years during which declining reserves and foreign-exchange shortages contributed to pressure on the naira and created difficulties for businesses seeking dollars for imports, international obligations and other legitimate transactions.
The rise in external reserves could also provide additional support for the naira.
Foreign reserves give the CBN greater capacity to manage excessive volatility in the foreign-exchange market and provide confidence that the country has sufficient foreign currency to meet its external obligations.
The recent improvement in reserves has coincided with greater stability in the FX market and a strengthening of the naira.
Market participants have closely monitored the relationship between the accumulation of reserves and developments in the exchange rate, particularly as the CBN seeks to build a more predictable and transparent foreign-exchange market.
However, analysts caution that a rise in reserves should not be interpreted as a guarantee that the naira will continue appreciating indefinitely.
The exchange rate remains influenced by several factors, including oil production and prices, foreign portfolio and direct investment, import demand, capital flows, inflation and monetary policy.
The reserve accumulation is also expected to improve Nigeria’s standing among international investors.
A country with stronger external buffers is generally perceived as better positioned to withstand external financial shocks and meet foreign-currency obligations.
For Nigeria, the development could help reinforce confidence among foreign investors who have previously expressed concerns about access to foreign exchange, exchange-rate volatility and the ability to repatriate investment proceeds.
The increase in reserves could therefore complement the Federal Government’s broader economic reforms aimed at improving the investment environment and restoring macroeconomic stability.
Despite the positive development, the increase in reserves does not by itself resolve all of Nigeria’s economic challenges.
The country continues to grapple with high inflation, elevated living costs, infrastructure constraints, unemployment and pressure on household incomes.
Similarly, the sustainability of reserve accumulation will depend significantly on the country’s ability to maintain stable and predictable foreign-exchange inflows.
Nigeria’s oil sector remains particularly important in this regard. Higher crude oil production, improved security in oil-producing communities, investment in upstream operations and stronger export earnings could support continued reserve accumulation.
Conversely, a sharp decline in oil prices or production could put pressure on foreign-exchange earnings.
The government’s efforts to diversify the economy and increase non-oil exports will therefore remain important to the long-term strength of Nigeria’s external position.
The latest reserve figures also provide an important backdrop to the reforms being implemented by the CBN under Cardoso.
Since taking office, the governor has repeatedly emphasised the need to restore confidence in Nigeria’s foreign-exchange market, improve price discovery and strengthen the country’s external buffers.
The authorities have sought to move the FX market towards greater transparency while addressing longstanding distortions that had contributed to a wide gap between official and parallel-market exchange rates.
The accumulation of reserves suggests that the reforms, alongside improved inflows, are beginning to produce a stronger external position.
Nevertheless, maintaining that progress will require continued policy consistency.
For the Nigerian economy, the significance of the latest reserve figure extends beyond the headline number.
Higher reserves can help strengthen the country’s ability to pay for essential imports, service external obligations and respond to periods of pressure in the foreign-exchange market.
It can also provide a psychological boost to businesses and investors following years of uncertainty surrounding the availability and cost of foreign currency.
The challenge for policymakers will now be to ensure that the gains are sustained and translated into broader improvements in economic conditions.
A stronger reserve position, combined with increased oil production, improved non-oil exports, disciplined monetary policy and greater foreign investment, could provide a more durable foundation for macroeconomic stability.
With reserves now above the $54 billion mark, attention will increasingly turn to whether Nigeria can sustain the accumulation through the remainder of the year.
The CBN’s ability to maintain a healthy reserve position while allowing the foreign-exchange market to function efficiently will be crucial.
For Cardoso and the monetary authorities, the latest figures represent a significant milestone in the effort to rebuild Nigeria’s external buffers.
For households and businesses, however, the ultimate test will be whether the improvement in reserves translates into a more stable naira, greater availability of foreign exchange, lower inflationary pressures and improved economic confidence.
The latest development is therefore both a major achievement and a test of the sustainability of Nigeria’s ongoing economic reforms.
With reserves now at their strongest level in almost two decades, Nigeria enters the next phase of its economic recovery with a considerably larger external financial cushion than it had at the beginning of the year.